ADHD money management means building simple, outside-your-head systems for paying bills, budgeting and saving that work with an ADHD brain, rather than relying on memory and willpower. It matters because missed payments, late fees and money avoidance can quietly snowball into debt and stress, yet most of these problems come from differences in executive function, not character.
If you have ever found a pile of unopened post, paid a late fee on a bill you could easily afford, or opened your banking app and felt instant dread, you are not alone. And you are not “bad with money”. You are managing money with a brain that finds planning, remembering and boring admin genuinely harder.
This guide explains the science, then shares practical ADHD money management strategies you can start this week.
Why ADHD Money Management Feels So Hard
Money is really a long list of executive function tasks. Remembering due dates. Opening letters. Tracking what is left until payday. Each one draws on working memory, planning and the ability to start dull tasks, which are all areas ADHD affects.
The scale is significant. The NHS England ADHD Taskforce says the best research suggests about 2–3% of adults have ADHD, yet far fewer have a diagnosis or support. It also estimates that untreated ADHD costs the UK around £17 billion a year.
Research backs up what many adults live with every day. A 2026 study of 3,717 adults in BMC Psychiatry found that higher ADHD symptoms were linked to greater odds of being in debt, even after accounting for income, anxiety and depression. Similarly, a large Swedish population study in Science Advances found that adults with ADHD start adulthood with normal credit use but are more likely to fall behind and experience financial distress over time.
Common patterns include:
- Time blindness: bills feel far away until they are overdue. Our complete guide to time blindness explains why.
- Admin avoidance: a brown envelope can trigger dread, so it goes on the pile.
- Working memory gaps: forgetting subscriptions, direct debits or things you have already bought.
- Impulsive spending: purchases deliver a quick dopamine hit, which we explore in why ADHD makes you spend without thinking.
- The “ADHD tax”: late fees, unused subscriptions and replacement costs that quietly add up.
It Is Not Laziness: What the Evidence Says
For years, people who struggle with bills have been judged as careless. However, the Money and Mental Health Policy Institute reviewed the research and found that people with ADHD often struggle to resist impulses, and that consumers with mental health problems are three times more likely to be in financial distress.
For too long, it’s been assumed that when people with mental health problems get behind on bills, or struggle to stick to their budget, it’s because they’re lazy or incompetent. Our research proves beyond doubt that’s just not true.
Polly Mackenzie, then Director of the Money and Mental Health Policy Institute (2017)
That shift matters for ADHD money management. When you stop blaming yourself, you can start designing around the real problem.
Practical ADHD Money Management Strategies
1. Automate everything you can
The fewer things you have to remember, the better. Set up direct debits for fixed bills to leave the day after payday, and move a set amount into savings on the same day. Automation turns “remember to pay” into “it just happens”.
2. Use a simple pots system
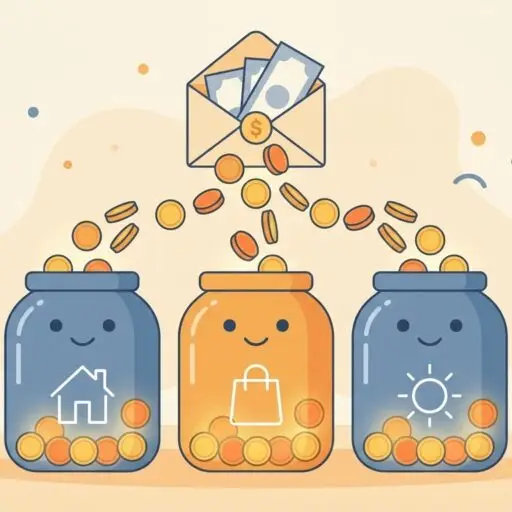
Many banks let you create pots or spaces. Try one for bills, one for everyday spending and one for savings. When payday lands, bills and savings go first, so whatever is left in your spending pot is genuinely yours to spend.
3. Make money visible
Out of sight really is out of mind. Turn on instant spending notifications, and give savings pots vivid names like “Cornwall in August” rather than “Savings”. A one-page budget stuck on the fridge beats a complex spreadsheet you never open.
4. Book a weekly 15-minute “money date”
Pick a regular slot, pair it with something pleasant, like a favourite playlist, and keep it short. Check balances, open post and cancel one unused subscription. A body double, like a friend on a video call, can make starting much easier.
5. Tame the post pile
Keep one tray by the door for all post. During your money date, sort it into three piles: act, file, recycle. Facing the dread in a predictable, time-limited way is far easier.
6. Get free help early if debt builds
If debt feels unmanageable, free and confidential advice is available from MoneyHelper, the government-backed guidance service, and debt charities such as StepChange. Asking early usually gives you more options. If money worries are affecting your mood or sleep, speak to your GP too.
Using the Dream SMART Framework for Money Goals
The Dream SMART Framework is a goal-setting approach designed specifically for adults with ADHD. It keeps the useful structure of traditional SMART goals (Specific, Measurable, Achievable, Relevant and Time-bound) but adds the missing ingredient: the Dream.
Traditional SMART goals quietly assume steady motivation, accurate time perception and consistent follow-through. Those are exactly the things ADHD makes unreliable. “Save £100 a month” is sensible, but it rarely survives the first tempting sale. Dream SMART starts instead with a vivid, emotional picture of what success looks and feels like, such as opening your banking app without a knot in your stomach.
That emotional “why” recruits interest, which is the fuel an ADHD brain runs on. Goals still have structure and deadlines, but they use flexible checkpoints and are reviewed week by week, often with a coach. Dream SMART is for adults with ADHD, diagnosed or still waiting, who have tried standard goal-setting and found it falls apart once the novelty fades. You can read more about why ADHD goal-setting fails and what might help.
An ADHD money management goal written the Dream SMART way might be: “By 1 December, I’ll have £300 in my ‘Stress-Free Christmas’ pot, so I can enjoy the holidays without dreading January.”
| Element | Traditional SMART | Dream SMART |
|---|---|---|
| Specific | A precise, narrow target, e.g. “save £100 a month” | A precise target anchored to a vivid picture of financial calm |
| Measurable | Tracked by numbers alone | Tracked by progress and how you feel about money, since ADHD motivation is interest-led |
| Achievable | Set as realistic once, up front | Scaled week by week to your actual executive function capacity |
| Relevant | Tied to a broader objective | Tied explicitly to your personal “why” to recruit interest |
| Time-bound | A single fixed deadline | Flexible checkpoints with built-in accountability check-ins |
| Driver (unique to Dream SMART) | Not included | A named Dream: the emotionally compelling vision that keeps you going when willpower fades |
When to Get Extra Support
Strategies work best when they are tailored to you. If you have tried apps and spreadsheets before and they faded after a fortnight, that is not failure. It is a sign you need a system built around how your brain actually works, plus some accountability to keep it going.
Coaching can make ADHD money management feel far less lonely. A coach can help you spot your personal money patterns, design routines that stick and adjust them when life changes. If you would like support, find out more about working with an ADHD coach.
Remember, good ADHD money management is not about becoming a different person. It is about building a few reliable systems, so your future self has less to remember and more to enjoy.
Frequently Asked Questions
ADHD affects executive functions such as working memory, planning, time perception and impulse control. These skills underpin everyday money tasks like remembering bills, budgeting and resisting impulse buys. Research links higher ADHD symptoms with greater odds of debt, but the cause is how the brain manages tasks, not laziness or a lack of intelligence.
The “ADHD tax” is an informal term for the extra costs that build up because of ADHD symptoms. Examples include late payment fees, unused subscriptions, duplicate purchases, replacing lost items and overdraft charges. Automating bills, turning on spending alerts and reviewing subscriptions regularly can reduce it significantly.
The best method is usually the simplest one you will actually use. Many adults with ADHD do well with a pots-based system: separate pots for bills, spending and savings, with bills and savings moved automatically on payday. Visual reminders, spending notifications and a short weekly money check-in help keep it on track.
In the UK, free, confidential debt advice is available from MoneyHelper, the government-backed money guidance service, and from charities such as StepChange, National Debtline and Citizens Advice. They can help you prioritise bills, talk to creditors and explore your options. Seeking advice early usually gives you more choices and less stress.
Yes. ADHD coaching supports ADHD money management through practical systems and accountability rather than lectures. A coach can help you identify your money patterns, set motivating goals using approaches like the Dream SMART Framework, build routines such as a weekly money check-in, and adjust strategies when they stop working.